Published result
Supplemental five-session cohort
This bounded result is scoped to the cohort and source snapshot below. It describes the observed sample; it does not complete the broader planned study, predict prices or recommend trades.
Observed in this cohort
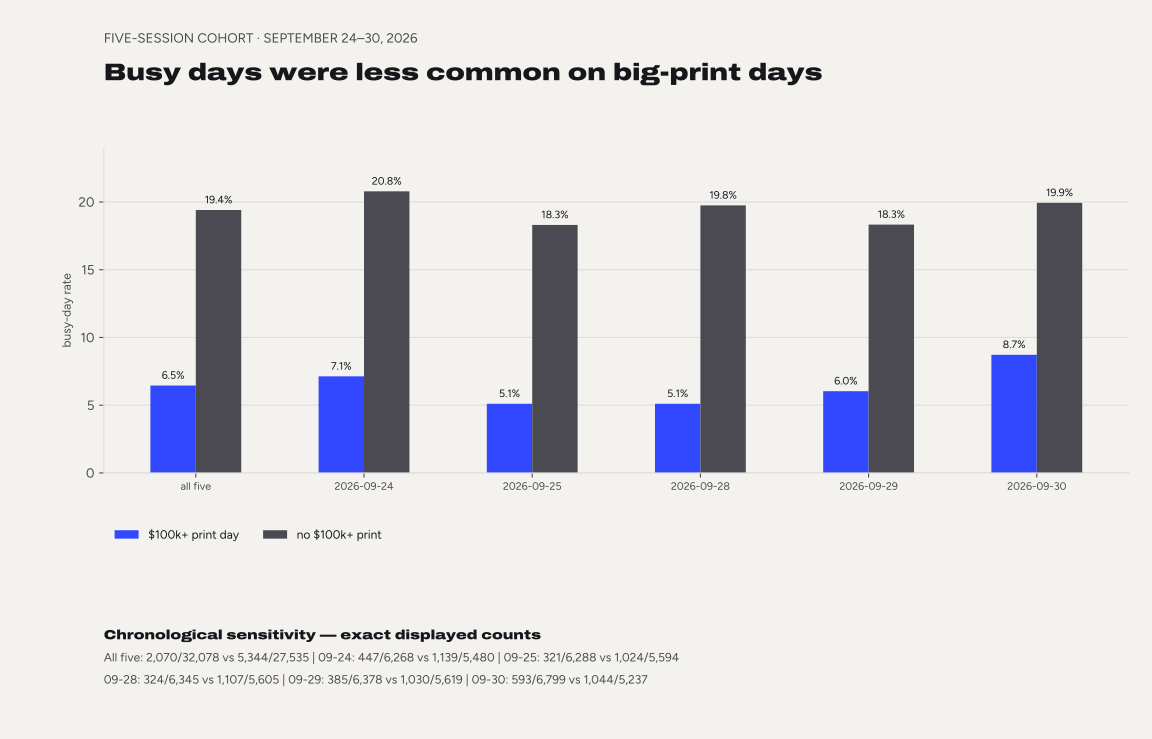
- 6.45% of security-days containing $100k+ prints were busy, compared with 19.4% of security-days without them.
- Coverage
- Sep 24 to Sep 30, 2026
- Cohort
- Archive-covered securities with 20 prior covered sessions in a selected 25-session window. Big means at least $100,000; busy means daily dollars excluding those prints are at least twice the prior 20-session median of total eligible dollars.
- Securities
- 12,067
- Ticker-days
- 59,613
All five sessions
- Busy days among $100k+ print days
- 6.45%2,070 of 32,078
- Busy days among days without $100k+ prints
- 19.4%5,344 of 27,535
- $100k+ print days among busy days
- 27.9%2,070 of 7,414
- Busy days overall
- 12.4%7,414 of 59,613
2026-09-24
- Busy days among $100k+ print days
- 7.13%447 of 6,268
- Busy days among days without $100k+ prints
- 20.8%1,139 of 5,480
- $100k+ print days among busy days
- 28.2%447 of 1,586
- Busy days overall
- 13.5%1,586 of 11,748
2026-09-25
- Busy days among $100k+ print days
- 5.10%321 of 6,288
- Busy days among days without $100k+ prints
- 18.3%1,024 of 5,594
- $100k+ print days among busy days
- 23.9%321 of 1,345
- Busy days overall
- 11.3%1,345 of 11,882
2026-09-28
- Busy days among $100k+ print days
- 5.11%324 of 6,345
- Busy days among days without $100k+ prints
- 19.8%1,107 of 5,605
- $100k+ print days among busy days
- 22.6%324 of 1,431
- Busy days overall
- 12.0%1,431 of 11,950
2026-09-29
- Busy days among $100k+ print days
- 6.04%385 of 6,378
- Busy days among days without $100k+ prints
- 18.3%1,030 of 5,619
- $100k+ print days among busy days
- 27.2%385 of 1,415
- Busy days overall
- 11.8%1,415 of 11,997
2026-09-30
- Busy days among $100k+ print days
- 8.72%593 of 6,799
- Busy days among days without $100k+ prints
- 19.9%1,044 of 5,237
- $100k+ print days among busy days
- 36.2%593 of 1,637
- Busy days overall
- 13.6%1,637 of 12,036
Limitations
- Fixed-$100k sensitivity analysis, not the planned Top 100 or Top 0.1% study; a fixed floor is not equally unusual across securities.
- Only five selected September 2026 sessions. Covers archive securities without verified stock/ETF-only classification or venue splits; missing prior histories are excluded and counted in provenance.
- Prior-session baseline includes all eligible dollars; current-day dollars exclude all $100k+ prints to remove their direct contribution. Uses the full source session including extended hours.
- Descriptive co-occurrence only. Pooling gives equal weight to security-days; observations are dependent, so no independent-sample confidence intervals or significance claims are reported.
- The fixed-threshold cohort has security-mix and selected-session limitations; the comparison is descriptive co-occurrence and makes no causal or edge claim.
Method busy-fixed100k-v1 · run Oct 17, 2026 · 11:10:37 PM ET · source snapshot 543346c9a7ea…
Published result
Current archive cohort · five-session fixed-$100k sensitivity
This bounded result is scoped to the cohort and source snapshot below. It describes the observed sample; it does not complete the broader planned study, predict prices or recommend trades.
Observed in this cohort
- 6.13% of security-days with a fixed-$100k+ print were busy (1,941 of 31,644), versus 16.85% without one (4,716 of 27,981).
- Across all security-days, 6,657 of 59,625 were busy (11.16%).
- Coverage
- Oct 27 to Nov 2, 2026
- Cohort
- Current archive-covered security IDs across five selected sessions, using a 20-session prior baseline; 3,333 security-days lacking the prior history were excluded and counted. This is not a point-in-time universe.
- Securities
- 12,091
- Ticker-days
- 59,625
- Rows
- 59,625
All five sessions · 2026-10-27 to 2026-11-02
- Busy days among $100k+ print days
- 6.13%1,941 of 31,644
- Busy days among days without $100k+ prints
- 16.9%4,716 of 27,981
- Busy days overall
- 11.2%6,657 of 59,625
Limitations
- Fixed-$100k sensitivity, not point-in-time Top-100 or Top-0.1% ranking.
- Pooled descriptive security-day co-occurrence; no confidence intervals or predictive/significance claims.
- Current survivor/archive-covered population and missing prior histories are explicit; not a historical point-in-time universe.
- Series identity is current native ETag/size; day-level inputs are hash-validated against immutable done receipts and matching manifests.
- The comparison is descriptive co-occurrence only; it is not a chronological forecast, causal result, significance claim, or profitability test.
Method busy-fixed100k-chronological-v1 · reviewed Nov 5, 2026 · 1:21:18 AM ET · source snapshot e45e6032a90c…
How to read this result
In the original September 24–30, 2026 fixed-$100,000 cohort, 6.45% of security-days with a big print were busy after those big-print dollars were removed, compared with 19.41% of security-days without a big print. A chronological sensitivity kept the direction and similar size: 6.12% versus 19.53% in the first two sessions, and 6.67% versus 19.32% in the last three.
The last-three-session split is a chronological holdout sensitivity, not a forecast or out-of-sample trading test. Security-days are dependent, the fixed floor is not equally unusual across securities, and the selected September 2026 sessions do not establish a general-market, causal, predictive or profitability result.
Study figure
The question
This study measures whether unusually large prints tend to occur on the same days as unusually high trading volume in the same ticker. It describes co-occurrence only, meaning how often the two happen together. It does not test whether either one leads to the other.
Why it matters to you
When a favorite has a big print, the day's volume may be heavy or light. Knowing how often big prints and busy days come together helps you read either case calmly.
There is a trap to avoid. A very large print adds to its day's volume by itself. A $500 million print in a stock that usually trades $300 million a day would make the day busy on its own. So the study takes each day's big prints out of that day's volume before it decides whether the day was busy.
Definitions
- Big print.
- An eligible print that ranked
Top 100 or higher for its ticker at the moment it printed. A second pass repeats every measure usingTop 0.1% prints . - Eligible print.
- A print that counts toward ranks under the method version in use, using corrected data. Canceled trades, and the reported trade types the method leaves out of ranks, do not count.
- Big-print day.
- A ticker-session with at least one big print.
- Dollar volume.
- The total of price times shares for all eligible regular-session trades in one ticker on one day.
- Relative volume.
- A day's dollar volume, with its big prints removed, divided by the median dollar volume of the previous 20 sessions.
- Busy day.
- A ticker-session with relative volume of 2.0 or more.
- Market-wide busy day.
- A session on which more than half of covered tickers had relative volume of 1.5 or more.
Population, window and eligibility
- Population.
- Archive-covered securities with at least 20 earlier covered sessions, included by this study’s eligibility rules.
- Window.
- From the first session with 20 earlier sessions of history, in early February 2016, to the last complete month before the study runs.
- Gaps.
- Ticker-sessions with incomplete data are left out, and the report counts them.
What we will measure and how we will report it
- How often a big-print day is a busy day, compared with how often any day is a busy day for the same tickers.
- The reverse view, how often a busy day contains a big print, compared with any day.
- All results with and without market-wide busy days, and split by stocks versus ETFs and by the venue type of the big print.
Results will appear as rates and ratios, each with its counts and a 95% interval. A ratio above one will mean the two occur together more often than they would if they were unrelated. It will not mean that either one causes the other. The report will name the method version used and the date the study ran.
Illustration
Sample chart for Big prints and busy days, drawn on made-up data.